ANNEXE 2
MARCHÉ AMÉRICAIN
Figure 9 : Corrélation USA avec portefeuille du
marché mondial CORRELATION USA
|
1 . 0 0 0 . 7 5 0 . 5 0 0 . 2 5 0 . 0 0 -0 . 2 5 -0 . 5 0 -0 .
7 5 -1 . 0 0
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
Figure 10 gain anticipé de la diversification
internationale USA
GAIN A N T IC IP É USA
|
8 6 4 2 0 -2 -4
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
MARCHÉ BRITANNIQUE
Figure 11 : Corrélation Grande Bretagne avec le
portefeuille du marché mondial CORRELATION G - B
|
1 . 0 0 0 . 7 5 0 . 5 0 0 . 2 5 0 . 0 0 -0 . 2 5 -0 . 5 0 -0 .
7 5 -1 . 0 0
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
. 1 6
. 1 2
. 0 8
. 0 4
. 0 0
-. 0 4
-. 0 8
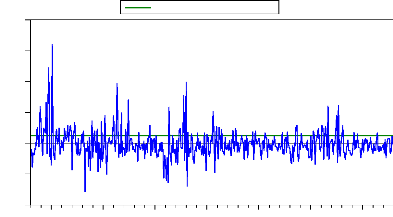
GAIN A N T IC IP É G B
Figure 12 : gain anticipé de la diversification
internationale Grande Bretagne
MARCHÉ JAPONAIS
Figure 13 : Corrélation du Japon avec le
portefeuille du marché mondial
CORRELATION JAPAN
|
1 . 0 0 0 . 7 5 0 . 5 0 0 . 2 5 0 . 0 0 -0 . 2 5 -0 . 5 0 -0 .
7 5 -1 . 0 0
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
. 2 0
. 1 5
. 1 0
. 0 5
. 0 0
-. 0 5
-. 1 0
-. 1 5
-. 2 0
-. 2 5
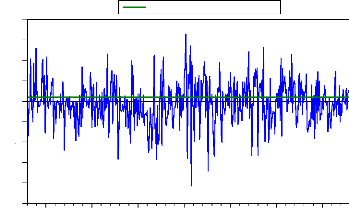
GAIN A N T IC IP É J A P O N
Figure 14 : gain anticipé de la diversification
internationale Japon
MARCHÉ DE H-KONG
Figure 15 : corrélation H-Kong avec le
portefeuille du marché mondial C O R R E L A T IO N H -K O N
G
|
1 . 0 0 0 . 7 5 0 . 5 0 0 . 2 5 0 . 0 0 -0 . 2 5 -0 . 5 0 -0 .
7 5
-1 . 0 0
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|

1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
6
4
2
0
-2
-4
-6
GAIN A N T IC IP É H-KONG
Figure 16 : gain anticipé de la diversification
internationale H-Kong
MARCHÉ DE SINGAPOUR
Figure 17 : corrélation Singapour avec le
portefeuille du marché mondial C O R R E L A T IO N S IN G A P
O U R
|
1 . 0 0 0 . 7 5 0 . 5 0 0 . 2 5 0 . 0 0 -0 . 2 5 -0 . 5 0 -0 .
7 5 -1 . 0 0
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
Figure 18 : gain anticipé de la diversification
internationale Singapour
GAIN A N T IC IP É S IN G A P O U R
|
. 1 0 . 0 8 . 0 6 . 0 4 . 0 2 . 0 0 -. 0 2 -. 0 4 -. 0 6
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
VARIABLES MACROÉCONOMIQUES
Figure 19 : Indice de la production industriel
USA
IN D IC E D E PRODUCTION IN D U S T R IE L AMÉRICAN
|
1 2 0 1 1 0 1 0 0 9 0 8 0 7 0 6 0 5 0 4 0 3 0
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
Figure 20 : Prime de défaut
PRIME D E D É F A U T
|
2 .8 2 .4 2 .0 1 .6 1 .2 0 .8 0 .4
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
Figure 21 : Prime de terme
PRIME D E T E R M E
|
6 4 2 0 -2 -4
|
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
|
Figure 22 : Inflation USA
INFLATION E T A T U N IS
|
6 0 0 5 0 0 4 0 0 3 0 0 2 0 0 1 0 0
0
|
|
1 9 7 5 1 9 8 0 1 9 8 5 1 9 9 0 1 9 9 5 2 0 0 0 2 0 0 5
RÉFÉRENCES
Adler M. et Dumas B. (1983), "International portfolio section and
corporation Finance : A synthesis", Journal of finance,38 : 925-984.
Akdogan, H. (1996). "A suggested approach to country selection in
international portfolio diversification".
Jornal of Portfolio Management, 23: 33-39.
Arouri, M. (2003). "Intégration financière et
diversification internationale de portefeuille". CNRS, Université Paris
X-Nanterre.
Baba, Y., Engle, R.F., Kroner, K.F, et Kraft, D.F. (1989)."
Multivariate simulataneous generalized ARCH".
UCSD Economics Woorking Paper Series 89-57r, Department of
Economics,University of California
At San Diego.
Black, F. (1976). "Studies of stock market volatility change".
Dans Proceedings of the 1976 meetings of
American Statistical Associations, pages 498-505. American
Statistical Associations.
Bekaert G. et Harvey C. (1995)," Time varying world market
integration", Journal of finance,50(2): 403- 444
Bollerslev, T. (1986). "Generalized autoregressive conditional
heteroskedasticity". Journal of Economics, 31: 307-327.
Bollerslev, T. (1990). "Modeling the coherence in short-run
nominal exchange Rates: A multvariate generalized ARCH approach". Review of
Economics and Statistic, 72: 458-508.
Carrieri F. (2001), "The Effects of liberalisation on market and
currency risk in the Eureupean Union", European financial management,7:
259-168.
De Santis, G. (1993)."Globalization of equity market : A test
using time-varying conditional moments". Working paper, University of Southern
California.
De Santis, G. et Gerard, B.(1997). "Intenational asset pricing
and portfolio diversification with time- varying risk". Journal of Finance,
52(4): 1881-1912.
De Santis, G. et Imrohoroglun S.(1995), "Stok return and
volatility in emerging financial markets", Working paper, Departement of
finance and business economics, University of Southen California.
Engle, R. et NG K. (1993), " Measuring and testing the impact on
news on volatility" Journal of finance,48: 1749:1778
Engle, R. F. (1982)."Autoregressive conditional
heteroskedasticity with estimates of the variance of United
Kingdom inflation". Economica, 50: 987-1008.
Gourieroux, C. (1996). Modèle GARCH et application
financières. Economica, Paris.
Kroner K. et NG. K. (1998),"Modeling asymmetric comovements of
asset returs", Review of financial Studies, 11: 817:844.
Lintner J. (1965), " The valuation of risky assets and the
selection of the risky investments in stok portfolios
And capital budgets", Reviews of economics and statistics, 47:
13-37
Ramsey, J. (1996). "If nonlinear models cannot forecast, What Use
are they?" Studies in Nonlinear Dynamics and Econometrics, 1(2): 65-86.
Solnik, B., Bourcelle, C., et Le Fur, Y. (1996)."International
market correlation and volatility". Financial Analysts Journal,52(5) :17-34
Markowitz,H.M. (1952). "Portfolio selection". Journal of
Finance,7(1) : 77-91.
Nelson,D.B. (1991). " Conditional heteroskedasticity in asset
returns : A new approch"
Econometrica, 59 : 347-370.
Sharpe W. (1964), "Capital asset prices : A theory of market
equilibrium under conditions of risk",Journal of
Finance, 9 :725-742
Turgeon, M.(1998). "La diversification internationale et les
cycles économiques". Mémoire de maîtrise, Université
du Québec à Montréal.
|